A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
How Reporting Might be Less Complex in 2025
January 1, 2025 · Accounting News, Blog
⏱ 4 min read
A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Understanding Carbon Accounting
December 1, 2024 · Accounting News, Blog
⏱ 3 min read
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Looking at accounting and journal entry considerations, if accounts receivables are debited and revenue is credited, it can be interpreted as the business recognizing revenue without the customer paying. As such, the U.S. Securities and Exchange Commission (SEC) sees the potential for intentional manipulation of earnings. It is important to review this type of transaction to see how the U.S. government and accounting standards treat deviations from these activities.
Defining Bill-and-Hold Arrangements
This type of agreement permits sellers to recognize revenue before delivery is made. Instead of shipping the product first, the seller bills the customer first, and delivery is arranged for a future date.
Based upon Accounting Standards Codification (ASC 606-10-55-83) and the U.S. Securities and Exchange Commission (SEC), for a customer to have obtained control of a product in a bill-and-hold arrangement, they must meet all of the following in order to move ownership of the product to the customer, with the seller still in custody of it.
Customers have explicitly asked for such an arrangement. Purchasers have to demonstrate a material reason for buying the goods through this route.
The goods must be sequestered explicitly for and attributed exclusively to the customer.
Customers must be able to physically receive the goods.
The separated goods are expressly prohibited from being used for any other purposes, including those of other customers.
Purchasers assume all risk.
There’s a written, fixed commitment to buy the goods.
The ultimate delivery of goods must be done according to a set timeline that follows realistic commercial uses.
The finished goods shall be 100 percent finished and be transit prepared.
Illustrating a Bill-and-Hold Arrangement
Companies in commodity-intensive establishments (miners, farmers, etc.) often use heavy equipment to recover and produce outputs. Since a mining or energy company is unsure of the profitability when recovering resources that are price-dependent on dynamic economic conditions, they often enter into a bill-and-hold arrangement with their supplier. Since the steel producer and the drilling company have an existing arrangement with standard terms, there’s an established history of bill-and-hold transactions. If machinery or drilling equipment is fully built for one of these companies, the equipment manufacturer will sequester the equipment and prohibit it from being shipped to any other buyer. Similarly, the invoice for the equipment must be satisfied by the customer in full within 30 days of the equipment being placed and waiting for the resource company buyers. The last step is for the buyer to arrange delivery in a reasonable manner.
Based on this real-world example, revenue should be recognized once it’s set aside exclusively for a particular mining or natural resource extraction company.
Considerations Beyond the Goods Themselves
Goods producers also must determine if there’s a custodial component during a bill-and-hold arrangement. If a custodial arrangement exists, either part of the original cost of goods sold to the customer needs to be determined or a separate charge, and therefore, exclusive recognition of revenue for the custodial services provided should be addressed outside of the bill-and-hold arrangement.
When it comes to revenue recognition under certain circumstances, goods producers may be able to recognize revenue despite the traditional requirement that goods have left a business, and the seller has materially satisfied their traditional requirement for accounting standards.
Breaking Down Bill-and-Hold Arrangements
November 1, 2024 · Accounting News, Blog
⏱ 3 min read
Looking at accounting and journal entry considerations, if accounts receivables are debited and revenue is credited, it can be interpreted as the business recognizing revenue without the customer paying. As such, the U.S. Securities and Exchange Commission (SEC) sees the potential for intentional manipulation of earnings. It is important to review this type of transaction to see how the U.S. government and accounting standards treat deviations from these activities.
Defining Bill-and-Hold Arrangements
This type of agreement permits sellers to recognize revenue before delivery is made. Instead of shipping the product first, the seller bills the customer first, and delivery is arranged for a future date.
Based upon Accounting Standards Codification (ASC 606-10-55-83) and the U.S. Securities and Exchange Commission (SEC), for a customer to have obtained control of a product in a bill-and-hold arrangement, they must meet all of the following in order to move ownership of the product to the customer, with the seller still in custody of it.
Customers have explicitly asked for such an arrangement. Purchasers have to demonstrate a material reason for buying the goods through this route.
The goods must be sequestered explicitly for and attributed exclusively to the customer.
Customers must be able to physically receive the goods.
The separated goods are expressly prohibited from being used for any other purposes, including those of other customers.
Purchasers assume all risk.
There’s a written, fixed commitment to buy the goods.
The ultimate delivery of goods must be done according to a set timeline that follows realistic commercial uses.
The finished goods shall be 100 percent finished and be transit prepared.
Illustrating a Bill-and-Hold Arrangement
Companies in commodity-intensive establishments (miners, farmers, etc.) often use heavy equipment to recover and produce outputs. Since a mining or energy company is unsure of the profitability when recovering resources that are price-dependent on dynamic economic conditions, they often enter into a bill-and-hold arrangement with their supplier. Since the steel producer and the drilling company have an existing arrangement with standard terms, there’s an established history of bill-and-hold transactions. If machinery or drilling equipment is fully built for one of these companies, the equipment manufacturer will sequester the equipment and prohibit it from being shipped to any other buyer. Similarly, the invoice for the equipment must be satisfied by the customer in full within 30 days of the equipment being placed and waiting for the resource company buyers. The last step is for the buyer to arrange delivery in a reasonable manner.
Based on this real-world example, revenue should be recognized once it’s set aside exclusively for a particular mining or natural resource extraction company.
Considerations Beyond the Goods Themselves
Goods producers also must determine if there’s a custodial component during a bill-and-hold arrangement. If a custodial arrangement exists, either part of the original cost of goods sold to the customer needs to be determined or a separate charge, and therefore, exclusive recognition of revenue for the custodial services provided should be addressed outside of the bill-and-hold arrangement.
When it comes to revenue recognition under certain circumstances, goods producers may be able to recognize revenue despite the traditional requirement that goods have left a business, and the seller has materially satisfied their traditional requirement for accounting standards.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
What is How to Account for Stranded Assets?
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets.
How to Account for Stranded Assets
October 1, 2024 · Accounting News, Blog
⏱ 4 min read
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
What is How to Account for Stranded Assets?
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
According to EY, the convertible debt market saw whipsaw action in issuances. Between 2015 and 2019, average issuance varied between $40 billion and $45 billion. However, it dropped to $22 billion in 2022 but re-accelerated to $52 billion in 2023. While the levels of issuance varied, the way this type of debt is accounted for has remained much calmer.
Defining a Convertible Bond
A convertible bond is a type of debt security that gives the investor the right to exchange the bond, at certain milestones, for a pre-determined percentage of equity in the issuing company. This investment vehicle has both equity and debt features.
Since this type of investment gives investors the potential for equity conversion into a company, the debt/bond side of it may present investors with a nominal coupon remittance or a potentially zero-coupon payment. However, there are important accounting considerations for this type of investment vehicle via generally accepted accounting principles (GAAP) and International Financial Reporting Standards (IFRS).
IFRS
When it comes to IFRS, convertible bonds are considered blended securities because they are partially debt and partially equity. The debt piece is accounted for by discounting the principal and interest paid out to the bondholder at the company’s cost of straight debt. The following example illustrates how it’s calculated:
The business presents a 10-year, $250 million convertible bond, providing investors with a 2.5 percent coupon rate and a 9.5 percent straight cost of debt. Based on discounting these variables, the present value of the principal and coupon payments is: $182,805,096 (assuming end-of-year, annual coupons). To determine the equity proportion, we must take $250 million and subtract $182,805,096, which equals $67,194,904.
Looking at the journal entry, we have the following breakdown:
Looking at the interest expense this is calculated as follows:
The 9.5 percent (straight debt cost) is multiplied by the net present value of the beginning debt liability balance of the first year ($182,805,096), which is $17,366,484.12. Since there’s a coupon payment of (2.5 percent X $250,000,000 = $6,250,000), the difference between $17,366,484.12 and $6,250,000 = $11,116,484.12 should be “accreted” to the debt liability or the debt balance.
The journal entry would be as follows:
Debit: Interest Expense $17,366,484.12
Credit: Cash $6,250,000
Credit: Accretion of Debt Discount – Liability = $11,116,484.12
Now, if at the bond’s maturity, the investor is unable to convert the bond to equity according to the terms of the convertible note, the entire $250 million bond will be paid back to the investor. The journal entry will be as follows:
Debit: Convertible Debt $250,000,000
Credit: Cash $250,000,000
If, however, the investor of the convertible bond is favorable to it being exchanged, the journal entry will be as follows:
Debit: Convertible Debt $250,000,000
Credit: Share Capital – Shareholder’s Equity = $250,000,000
This explanation assumes that convertible bonds are only able to be converted into company equity. However, if the bond is cash-settled, there are alternate considerations. It’s also assumed that the bond is issued at year’s end and makes its coupon payments once a year.
GAAP
Under generally accepted accounting principles (GAAP), present standards treat it as straight debt. This accounting practice changed from GAAP’s previous treatment of bifurcating it, similar to IFRS’ current treatment.
At issuance, the journal entries are as follows:
Debit: Cash $250,000,000
Credit: Convertible Debt $250,000,000
With this accounting treatment, it’s recognized as an interest expense. Since this contrasts with IFRS, no accretion is required under GAAP. This assumes there are no additional debt issuance costs when calculating interest expenses. Therefore, assuming the same initial debt amount at par and the coupon rate for year one, it’s the rate for the debt issuance multiplied by the full debt amount ($250,000,000).
The journal entry is as follows:
Debit: Interest Expense $6,250,000
Credit: Cash $6,250,000
If the convertible debt doesn’t present a good opportunity for the investor, they’ll receive the principal back. The journal entry is as follows:
Debit: Convertible Debt $250,000,000
Credit: Cash $250,000,000
If, however, the convertible debt presents the investor with an opportunity to convert to equity, and it’s exercised, the journal entry is presented as follows:
Debit: Convertible Debt $250,000,000
Credit: Share Capital – Shareholder’s Equity $250,000,000
Conclusion
While these examples do not explore all the potential scenarios when accounting for convertible debt, they show what considerations accountants must keep in mind when analyzing a transaction.
Accounting for Convertible Debt Instruments
September 1, 2024 · Accounting News, Blog
⏱ 4 min read
According to EY, the convertible debt market saw whipsaw action in issuances. Between 2015 and 2019, average issuance varied between $40 billion and $45 billion. However, it dropped to $22 billion in 2022 but re-accelerated to $52 billion in 2023. While the levels of issuance varied, the way this type of debt is accounted for has remained much calmer.
Defining a Convertible Bond
A convertible bond is a type of debt security that gives the investor the right to exchange the bond, at certain milestones, for a pre-determined percentage of equity in the issuing company. This investment vehicle has both equity and debt features.
Since this type of investment gives investors the potential for equity conversion into a company, the debt/bond side of it may present investors with a nominal coupon remittance or a potentially zero-coupon payment. However, there are important accounting considerations for this type of investment vehicle via generally accepted accounting principles (GAAP) and International Financial Reporting Standards (IFRS).
IFRS
When it comes to IFRS, convertible bonds are considered blended securities because they are partially debt and partially equity. The debt piece is accounted for by discounting the principal and interest paid out to the bondholder at the company’s cost of straight debt. The following example illustrates how it’s calculated:
The business presents a 10-year, $250 million convertible bond, providing investors with a 2.5 percent coupon rate and a 9.5 percent straight cost of debt. Based on discounting these variables, the present value of the principal and coupon payments is: $182,805,096 (assuming end-of-year, annual coupons). To determine the equity proportion, we must take $250 million and subtract $182,805,096, which equals $67,194,904.
Looking at the journal entry, we have the following breakdown:
Looking at the interest expense this is calculated as follows:
The 9.5 percent (straight debt cost) is multiplied by the net present value of the beginning debt liability balance of the first year ($182,805,096), which is $17,366,484.12. Since there’s a coupon payment of (2.5 percent X $250,000,000 = $6,250,000), the difference between $17,366,484.12 and $6,250,000 = $11,116,484.12 should be “accreted” to the debt liability or the debt balance.
The journal entry would be as follows:
Debit: Interest Expense $17,366,484.12
Credit: Cash $6,250,000
Credit: Accretion of Debt Discount – Liability = $11,116,484.12
Now, if at the bond’s maturity, the investor is unable to convert the bond to equity according to the terms of the convertible note, the entire $250 million bond will be paid back to the investor. The journal entry will be as follows:
Debit: Convertible Debt $250,000,000
Credit: Cash $250,000,000
If, however, the investor of the convertible bond is favorable to it being exchanged, the journal entry will be as follows:
Debit: Convertible Debt $250,000,000
Credit: Share Capital – Shareholder’s Equity = $250,000,000
This explanation assumes that convertible bonds are only able to be converted into company equity. However, if the bond is cash-settled, there are alternate considerations. It’s also assumed that the bond is issued at year’s end and makes its coupon payments once a year.
GAAP
Under generally accepted accounting principles (GAAP), present standards treat it as straight debt. This accounting practice changed from GAAP’s previous treatment of bifurcating it, similar to IFRS’ current treatment.
At issuance, the journal entries are as follows:
Debit: Cash $250,000,000
Credit: Convertible Debt $250,000,000
With this accounting treatment, it’s recognized as an interest expense. Since this contrasts with IFRS, no accretion is required under GAAP. This assumes there are no additional debt issuance costs when calculating interest expenses. Therefore, assuming the same initial debt amount at par and the coupon rate for year one, it’s the rate for the debt issuance multiplied by the full debt amount ($250,000,000).
The journal entry is as follows:
Debit: Interest Expense $6,250,000
Credit: Cash $6,250,000
If the convertible debt doesn’t present a good opportunity for the investor, they’ll receive the principal back. The journal entry is as follows:
Debit: Convertible Debt $250,000,000
Credit: Cash $250,000,000
If, however, the convertible debt presents the investor with an opportunity to convert to equity, and it’s exercised, the journal entry is presented as follows:
Debit: Convertible Debt $250,000,000
Credit: Share Capital – Shareholder’s Equity $250,000,000
Conclusion
While these examples do not explore all the potential scenarios when accounting for convertible debt, they show what considerations accountants must keep in mind when analyzing a transaction.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.



 Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
 Looking at accounting and journal entry considerations, if accounts receivables are debited and revenue is credited, it can be interpreted as the business recognizing revenue without the customer paying. As such, the U.S. Securities and Exchange Commission (SEC) sees the potential for intentional manipulation of earnings. It is important to review this type of transaction to see how the U.S. government and accounting standards treat deviations from these activities.
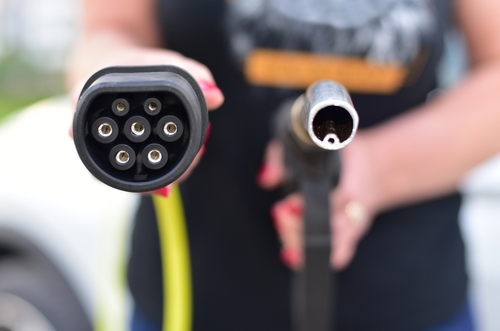 With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
 According to EY, the convertible debt market saw whipsaw action in issuances. Between 2015 and 2019, average issuance varied between $40 billion and $45 billion. However, it dropped to $22 billion in 2022 but re-accelerated to $52 billion in 2023. While the levels of issuance varied, the way this type of debt is accounted for has remained much calmer.