What is Innocent Spouse Relief?

5 min read

What is Innocent Spouse Relief?The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.

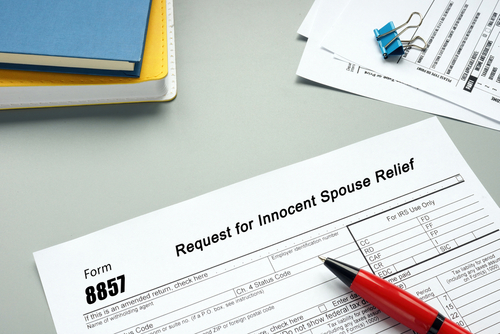
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.

Qualifications for Innocent Spouse Relief

To qualify, you must meet several conditions.

  • Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
  • Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
  • Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
  • Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.

What Doesn’t Qualify for Innocent Spouse Relief?

Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:

  • Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
  • Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
  • Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.

Pros and Cons of Filing

Advantages include:

  • Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
  • Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
  • Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.

Potential drawbacks are:

  • No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
  • Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
  • Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
  • Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.

Conclusion

To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.

After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.

What is Innocent Spouse Relief?
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing.

Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government Spending

3 min read

Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government SpendingAll bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.

Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.

BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.

Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.

Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.

Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.

Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.

Energy Tax Credit Changes For 2025

3 min read

Energy Tax Credit Changes For 2025The coming shakeup of the executive branch, along with Republican control of both houses of Congress, means tax changes are highly likely in 2025 and beyond. Positioning for new and amended tax provisions is already off to the races.
Regardless of the political landscape, on rare occasions, some measures have broad bipartisan support. One such bill is called the Methane Reduction and Economic Growth Act. It proposes adding a new credit for sequestering “qualified” methane from mining activities.

Looking Ahead To 2025

Proponents of the Methane Reduction and Economic Growth Act hope the tax credit will have a beneficial economic impact and create jobs. The idea is to capture and utilize the methane for productive industrial uses or as an alternative for heating buildings. The methane emitted by mines that qualify have long lifespans, with some abandoned mines emitting methane for up to 100 years. The long lifespan of the methane source is hoped to support the significant capital investment required to get the process up and running.

There is also significant potential for job creation in areas most impacted by the shutdown of coal-fired power plants, which in turn devastated the coal mining industry. The concept of using mine methane as an energy source could support rural American jobs.

Landscape and Potential for the Credit

There is a lot of mine methane to capture, with most not currently being captured. The U.S. government estimates abandoned coal mines produce about 237,000 metric tons annually. This methane has many potential uses, including hydrogen production.

Details on the New Subsection

The new section of 45Q credits would be based on the quantity of qualified methane that is sequestered. The captured methane must then be sent to the pipeline and used for producing heat or electricity. To be considered “qualified methane,” it must be captured from certain types of mines, including closed, abandoned, and surface mines. Finally, the methane captured must have otherwise been sent into the atmosphere if it had not been for the capture equipment activity.

Only qualified facilities may obtain the credit. Among other factors, the taxpayer needs to capture a minimum of 2,500 metric tons of methane each year to qualify. There are a lot more technical regulatory requirements related to the specific nature of methane capture, but those are beyond the scope of this article.

Conclusion

Typically, tax bills are split down the aisle based on political partisanship. This makes the passage of tax legislation difficult at best due to competing interests and a divided government. The tax credits related to methane capture, however, appear to be unusually bipartisan in nature. This is due to the unique intersection of democratic support from an environmental and climate perspective, meeting with Republican interest to support economic development in rural coal mining areas where the industry has been devastated. Put these two interests together, and you have the makings for a widely supported bipartisan bill that is very likely to pass.

Understanding Carbon Accounting

3 min read

Understanding Carbon Accounting, what is Carbon AccountingAlso known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions. 
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.

Environmental, Social & Governance

Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.

It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.  

Calculating Emissions

1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.  

2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.

3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.    

According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.

From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.

Compliance

While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.

Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.

Conclusion

The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.

Common Business Accounting Calculations

3 min read

Common Business Accounting CalculationsNo matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.

Break-Even Analysis

This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.

Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.

Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)

This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.

Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.

Another way to determine a company’s break-even point is as follows:

Contribution Margin = Item Price – Variable Cost Per Unit

This is illustrated by: $55 = ($85 – $30)

The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.

Cash Ratio Formula

The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.

It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.

It’s calculated as follows: Cash Ratio: Cash + Cash Equivalents/Current Liabilities.

Gross Profit Margin

This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.

It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100

Debt-to-Equity (D/E) Ratio

This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.

It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.

While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.