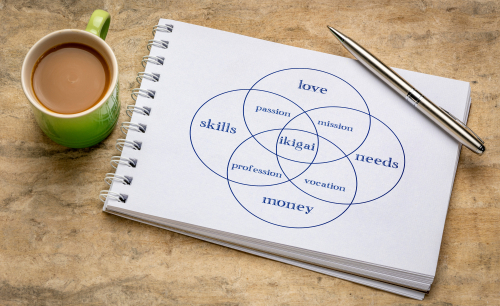
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Pre-Retirement Planning Guide – Finding Purpose In Life
December 1, 2024 · Blog, Financial Planning
⏱ 5 min read
Step 7: Find Your Raison d’Etre
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Understanding Carbon Accounting
December 1, 2024 · Accounting News, Blog
⏱ 3 min read
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government Spending
December 1, 2024 · Blog, Congress at Work
⏱ 3 min read
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Step 6: Looking to Legacy Planning to Address Future Needs of Family
How do you want to be remembered? People often view their legacy as a way of disseminating assets to charitable venues to be remembered as passionate and generous supporters. That is one aspect of a legacy.
But perhaps the most important legacy plan is how you want to be remembered by your family, friends and loved ones. If you do not develop an estate plan and communicate it with your loved ones, if you leave your financial accounts and investments in a state of disarray by not keeping files organized and beneficiaries updated, then you leave a huge burden behind when you pass away.
This may very well mar the fine memory your loved ones have for you. After all, having to manage a complex or messy estate over a long period of time could overwrite the previously fond memories they had for you. No one wants their legacy blemished by administrative chaos, so now is the time to get your financial house and estate plan in order. Don’t let the last memories of you be ones of aggravation and bitterness.
Repair and Strengthen Relationships
If you are estranged or have an uncomfortable relationship with someone close to you, do yourself and them a favor by rectifying the situation. This may take time, so begin the process during your pre-retirement planning phase. Remember, no one wants to die having said harsh last words or having not seen a loved one for a long time.
Make part of your plan a commitment to shore up relationships. You can start by making a list of people with whom you should contact, jotting down a few thoughts about what you want to communicate, and devising a plan for how to accomplish this. It might be a special weekend with each of your children, or inviting a long-lost sibling to take a vacation with you, or taking your spouse out to dinner and reiterating your love for one another. Remember, your legacy is about how you want to be remembered, so make some new memories to crowd out any poor ones.
First, Loved Ones; Then Philanthropy
Once your relationships are in good shape (which takes ongoing maintenance – it’s not a one-shot deal), turn your attention to your philanthropic legacy. This includes how you want to distribute your assets to both your family and the causes you care about.
The following are some key components of a legacy plan:
Wealth Transfer
Be sure that your estate plan efficiently communicates and transfers your assets to the appropriate heirs. It also should incorporate prudent tax planning so that your beneficiaries do not pay more in taxes than required. Remember, part of your legacy will be determined by how well you protect your assets, not just from taxes but also from creditors, divorce settlements, and other potential risks.
Education
Leaving a large sum to heirs can be overwhelming. It’s a good idea to help them learn about financial responsibility, wealth management and philanthropy. By helping them understand tactics about which assets to leave intact, which to transfer to other accounts and which they can liquidate for their own use – in a tax-proficient manner – is key to ensuring they’re ready to manage the legacy you pass on.
Charitable Giving
There is a range of sophisticated vehicles that allow you to maximize the long-term value of gifted assets to charitable and passion causes. For example, a donor-advised fund (DAF) enables you to donate cash or securities to a charity-sponsored fund and help direct where charitable grants are distributed. Another option is to set up a private foundation. This is a public 501(c)(3) organization that invests, manages, and distributes your donations to charities; however, this option is really only viable and cost-efficient if you have substantial assets (multi-millions) in your estate.
There are also trust vehicles designed to balance your philanthropic goals with leaving enough assets for your own living expenses and/or an inheritance for heirs. Fortunately, these also may enjoy tax benefits, such as an upfront tax deduction, removing assets from your taxable estate, or avoiding capital gains taxes on donated securities. Here are some examples:
Charitable Lead Trust (CLT) – The charity of your choice receives trust income (fixed payment or fixed percentage) for a specified term/or your lifespan, after which the remainder goes either back to you or another trust beneficiary.
Charitable Remainder Trust (CRT) – The trust distributes income to you or another beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Charitable Remainder Unitrust (CRUT) – The trust distributes a fixed percentage of its balance to you or a beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Charitable Remainder Annuity Trust (CRAT) – The trust distributes a fixed payment to you or a beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Setting up a trust to meet a variety of goals is very complex. Be sure to work with an experienced and qualified estate planner to set this up or, again, your legacy could be tarnished if your estate is not disseminated as planned.
Pre-Retirement Planning Guide – Legacy Planning
November 1, 2024 · Blog, Financial Planning
⏱ 5 min read
Step 6: Looking to Legacy Planning to Address Future Needs of Family
How do you want to be remembered? People often view their legacy as a way of disseminating assets to charitable venues to be remembered as passionate and generous supporters. That is one aspect of a legacy.
But perhaps the most important legacy plan is how you want to be remembered by your family, friends and loved ones. If you do not develop an estate plan and communicate it with your loved ones, if you leave your financial accounts and investments in a state of disarray by not keeping files organized and beneficiaries updated, then you leave a huge burden behind when you pass away.
This may very well mar the fine memory your loved ones have for you. After all, having to manage a complex or messy estate over a long period of time could overwrite the previously fond memories they had for you. No one wants their legacy blemished by administrative chaos, so now is the time to get your financial house and estate plan in order. Don’t let the last memories of you be ones of aggravation and bitterness.
Repair and Strengthen Relationships
If you are estranged or have an uncomfortable relationship with someone close to you, do yourself and them a favor by rectifying the situation. This may take time, so begin the process during your pre-retirement planning phase. Remember, no one wants to die having said harsh last words or having not seen a loved one for a long time.
Make part of your plan a commitment to shore up relationships. You can start by making a list of people with whom you should contact, jotting down a few thoughts about what you want to communicate, and devising a plan for how to accomplish this. It might be a special weekend with each of your children, or inviting a long-lost sibling to take a vacation with you, or taking your spouse out to dinner and reiterating your love for one another. Remember, your legacy is about how you want to be remembered, so make some new memories to crowd out any poor ones.
First, Loved Ones; Then Philanthropy
Once your relationships are in good shape (which takes ongoing maintenance – it’s not a one-shot deal), turn your attention to your philanthropic legacy. This includes how you want to distribute your assets to both your family and the causes you care about.
The following are some key components of a legacy plan:
Wealth Transfer
Be sure that your estate plan efficiently communicates and transfers your assets to the appropriate heirs. It also should incorporate prudent tax planning so that your beneficiaries do not pay more in taxes than required. Remember, part of your legacy will be determined by how well you protect your assets, not just from taxes but also from creditors, divorce settlements, and other potential risks.
Education
Leaving a large sum to heirs can be overwhelming. It’s a good idea to help them learn about financial responsibility, wealth management and philanthropy. By helping them understand tactics about which assets to leave intact, which to transfer to other accounts and which they can liquidate for their own use – in a tax-proficient manner – is key to ensuring they’re ready to manage the legacy you pass on.
Charitable Giving
There is a range of sophisticated vehicles that allow you to maximize the long-term value of gifted assets to charitable and passion causes. For example, a donor-advised fund (DAF) enables you to donate cash or securities to a charity-sponsored fund and help direct where charitable grants are distributed. Another option is to set up a private foundation. This is a public 501(c)(3) organization that invests, manages, and distributes your donations to charities; however, this option is really only viable and cost-efficient if you have substantial assets (multi-millions) in your estate.
There are also trust vehicles designed to balance your philanthropic goals with leaving enough assets for your own living expenses and/or an inheritance for heirs. Fortunately, these also may enjoy tax benefits, such as an upfront tax deduction, removing assets from your taxable estate, or avoiding capital gains taxes on donated securities. Here are some examples:
Charitable Lead Trust (CLT) – The charity of your choice receives trust income (fixed payment or fixed percentage) for a specified term/or your lifespan, after which the remainder goes either back to you or another trust beneficiary.
Charitable Remainder Trust (CRT) – The trust distributes income to you or another beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Charitable Remainder Unitrust (CRUT) – The trust distributes a fixed percentage of its balance to you or a beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Charitable Remainder Annuity Trust (CRAT) – The trust distributes a fixed payment to you or a beneficiary for a specified term or your lifespan, after which the remainder goes to a designated charity.
Setting up a trust to meet a variety of goals is very complex. Be sure to work with an experienced and qualified estate planner to set this up or, again, your legacy could be tarnished if your estate is not disseminated as planned.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
It’s that time of year again. Halloween has just come and gone – and now we’re hurtling headlong into Thanksgiving and Christmas. For holiday shopping, it’s tempting to turn a blind eye and put everything on your credit cards. However, if you don’t want to have a financial hangover in January, February (and so on), you might want to take a look at these tips.
Create a Budget and Stick To It
The earlier you sit down and do this, the better. Decide on a financial cap per gift per person, then shop. Then, get creative. For instance, what if you bought a pre-loved item for someone? Made something for someone? You might also decide on a gift, then shop around and compare. So, when Black Friday and Prime Days raise their heads, you’ll already have made your selections. More on that below.
Put a Lid on Impulse Buying
This is a tough one. As mentioned above, Prime Day and Black Friday are hard to avoid. They scream at you on your TV and phone scroll, so it’s easy to get off track. If you want to avoid runaway spending, here are two ways to approach these retail spectacles. First, you can keep an eye on which item you want – then plan and research. Buy it when the price is crazy low, and walk away from all the frenzy, all the while tracking your spending. Second, you can dive right in, browse all you want, then put some things in your cart. But don’t buy it then. Come back a day later and decide if the purchase is really necessary. At this moment, you might also imagine the pain you could feel in 2025 with a bunch of debt hanging over your head. Employing this mindset could make all the difference.
Use Your Credit Cards Wisely
According to Jennifer Ellis, senior consumer manager at BOK Financial, credit card debt is on the rise. And with high interest rates, if you do have a balance, you’re going to pay more for your items. Before you set out to buy gifts, try to pay your credit card balances in full to avoid big fees. This way, you won’t carry the burden of a lot of debt into the new year.
Try Envelope Stuffing
This is an old trick, but a good one. Get envelopes, put the name of your giftee on the front, then put the amount of money you’re going to spend in it. Once you’ve used up the cash in the envelope for said person, you’re done. Also, using cash is more startling – you see the money go bye-bye! It’s so easy to gloss over the actual cash amount when you’re using plastic, as it almost doesn’t seem real. Working with real moolah is a tried-and-true technique, a wake-up call that you’ll appreciate.
Plan Early for Travel
Buy your tickets early for Thanksgiving and the December holidays. Monitor airline, bus, and train websites. Set alerts to notify you when the prices go up or down. All it takes is a little time and elbow grease. In the end, it’s worth it.
Most importantly, having a financial plan during this time of year is key. Yes, life is busy, but if you want to step into the new year without carrying the shackles of debt, using some of these ideas might be your saving grace.
It’s that time of year again. Halloween has just come and gone – and now we’re hurtling headlong into Thanksgiving and Christmas. For holiday shopping, it’s tempting to turn a blind eye and put everything on your credit cards. However, if you don’t want to have a financial hangover in January, February (and so on), you might want to take a look at these tips.
Create a Budget and Stick To It
The earlier you sit down and do this, the better. Decide on a financial cap per gift per person, then shop. Then, get creative. For instance, what if you bought a pre-loved item for someone? Made something for someone? You might also decide on a gift, then shop around and compare. So, when Black Friday and Prime Days raise their heads, you’ll already have made your selections. More on that below.
Put a Lid on Impulse Buying
This is a tough one. As mentioned above, Prime Day and Black Friday are hard to avoid. They scream at you on your TV and phone scroll, so it’s easy to get off track. If you want to avoid runaway spending, here are two ways to approach these retail spectacles. First, you can keep an eye on which item you want – then plan and research. Buy it when the price is crazy low, and walk away from all the frenzy, all the while tracking your spending. Second, you can dive right in, browse all you want, then put some things in your cart. But don’t buy it then. Come back a day later and decide if the purchase is really necessary. At this moment, you might also imagine the pain you could feel in 2025 with a bunch of debt hanging over your head. Employing this mindset could make all the difference.
Use Your Credit Cards Wisely
According to Jennifer Ellis, senior consumer manager at BOK Financial, credit card debt is on the rise. And with high interest rates, if you do have a balance, you’re going to pay more for your items. Before you set out to buy gifts, try to pay your credit card balances in full to avoid big fees. This way, you won’t carry the burden of a lot of debt into the new year.
Try Envelope Stuffing
This is an old trick, but a good one. Get envelopes, put the name of your giftee on the front, then put the amount of money you’re going to spend in it. Once you’ve used up the cash in the envelope for said person, you’re done. Also, using cash is more startling – you see the money go bye-bye! It’s so easy to gloss over the actual cash amount when you’re using plastic, as it almost doesn’t seem real. Working with real moolah is a tried-and-true technique, a wake-up call that you’ll appreciate.
Plan Early for Travel
Buy your tickets early for Thanksgiving and the December holidays. Monitor airline, bus, and train websites. Set alerts to notify you when the prices go up or down. All it takes is a little time and elbow grease. In the end, it’s worth it.
Most importantly, having a financial plan during this time of year is key. Yes, life is busy, but if you want to step into the new year without carrying the shackles of debt, using some of these ideas might be your saving grace.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 Step 7: Find Your Raison d’Etre



 Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
 All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
 Step 6: Looking to Legacy Planning to Address Future Needs of Family
 It’s that time of year again. Halloween has just come and gone – and now we’re hurtling headlong into Thanksgiving and Christmas. For holiday shopping, it’s tempting to turn a blind eye and put everything on your credit cards. However, if you don’t want to have a financial hangover in January, February (and so on), you might want to take a look at these tips.